
April Sees Robust Record Automotive Retail Sales In India
- By MT Bureau
- May 05, 2026
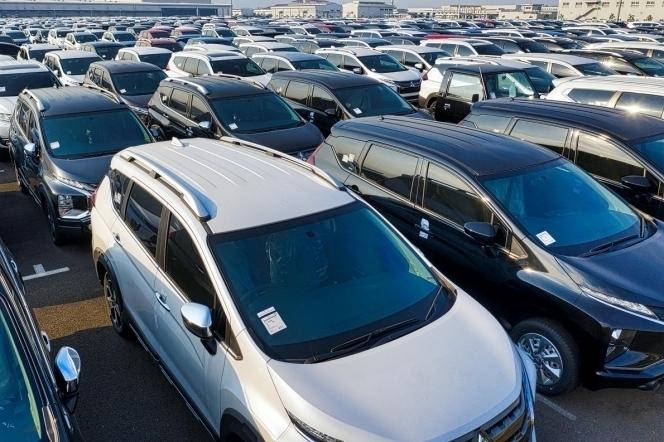
The positive momentum for the Indian automotive industry continues to accelerate in the new fiscal year. In what comes as a record retail sales registration across categories, the total automotive sales in April 2026 reached a whopping 2.61 million units, up 12.94 percent, as compared to 2.31 million units last year.
The record retail sales were witnessed across two-wheelers, which saw retail registrations at 1.91 million units, up 13 percent YoY, three-wheelers at 106,908 units, up 7.19 percent YoY, passenger vehicles at 407,355 units, up 12.21 percent YoY, tractors at 75,109 units, up 23.22 percent YoY and commercial vehicles at 99,339 unit, up 15.02 percent YoY.
Barring construction equipment at 6,348 units, down 2.25 percent YoY, all categories were in the green.
Sai Giridhar, President, FADA, said: “This clearly underlines that the structural demand momentum which defined the second half of FY2026 has carried into the new financial year. The sequential MoM softness of -3.01 percent reflects the customary post-March seasonal reset rather than any erosion in underlying demand.”
He stated that the demand engine remained broad-based with Urban markets growing 14.07 percent YoY and Rural markets growing 12.30 percent YoY.
The industry body attributed this performance to improved rural liquidity following a healthy rabi season, the extended marriage-season tailwind that runs through May and June, and continued affordability gains carried over from the GST 2.0 framework. Furthermore, the performance could have further grown, if the industry did not witness supply constraints for selective models in certain commuter and premium variants.
In terms of electrification in the two-wheeler segment, it saw moderation at 7.76 percent, as compared to 9.79 percent last month.
Commenting on the commercial vehicle performance, Giridhar said, “From a market mix standpoint, Rural markets grew a striking 20.25 percent YoY versus Urban at 10.22 percent YoY, highlighting that logistics-led demand is no longer concentrated in metros. Dealers across regions reported sustained freight movement, infrastructure-linked goods activity, school-bus replacement demand, and steady single-owner operator confidence as the principal drivers. The MCV sub-segment continued its standout run at 27.07 percent YoY, while LCVs grew 17.76 percent and HCVs 8.25 percent — reflecting participatory growth across sub-segments. Some dealers, however, flagged elongated financing turnaround time, sporadic variant-level supply gaps and a degree of caution induced by external geopolitical developments as monitorables.”
Coming to the passenger vehicle segment, the segment has seen demand firing on all cylinders. Interestingly, Rural PV growth at 20.40 percent YoY, was nearly three times the Urban pace of 7.11 percent YoY.
“This confirms the structural broadening of personal mobility into Tier-3 and rural India, supported by a small-car revival, sustained SUV demand and a richer alternative-powertrain product mix where CNG share held firm at 22.62 percent and EV share improved further to 5.77 percent. Dealers cited improved affordability post-GST 2.0, the Reserve Bank of India's supportive rate stance, which has translated into stronger EMI comfort, and a healthy marriage-season pipeline as the principal demand drivers. PV inventory levels have moved up modestly to a range of 28–30 days, marginally above March'26's around 28 days but well within the healthy band that we view as constructive. We continue to encourage PV OEMs to maintain disciplined dispatches in the coming weeks so that channel inventory stays anchored close to FADA's recommended 21-day benchmark, particularly as we move into the seasonally softer May-June window,” added Giridhar.
The near-term outlook for May 2026 is cautiously optimistic, with over 55 percent of dealers expecting continued growth. Momentum is expected to be maintained by the peak of the marriage season and residual buying from festivals like Akshaya Tritiya. However, monitorable factors include potential heatwaves, geopolitical tensions in West Asia that could impact fuel prices, and selective supply constraints. Over the next three months, dealer confidence remains steady as the industry transitions toward its mid-year phase.
Going forward, the industry body expects that demand for CVs, two-wheelers and passenger vehicles will continue to be positive. For CVs, he attributes the same to residual buying triggered by Akshaya Tritiya in select northern and western markets, the new financial-year OEM scheme cycle and sustained replacement demand in the CV segment.
The two-wheeler segment will continue to reap the benefits of improving rural cashflows, agri-cycle preparation purchases and continued post-GST 2.0 affordability in the rural market, while passenger vehicles are likely to benefit from healthy booking pipelines, refreshed product launches and improving small-car traction.
“That said, the India Meteorological Department's forecast of an above-normal heatwave across several states, the geopolitical situation in West Asia and its potential pass-through to fuel prices, selective supply constraints on running models remain factors to watch,” he concluded.
| AUTO RETAIL SALES IN INDIA | ||||||
| Category | Apr '26 | Apr '25 | Change (in units) | Change (in %) | Mar '26 | Change (in %) |
| YoY | YoY | MoM | ||||
| Two-wheeler | 1,916,258 | 1,695,638 | 220,620 | 13.01% | 1,951,006 | -1.78% |
| Three-wheeler | 106,908 | 99,741 | 7,167 | 7.19% | 109,777 | -2.61% |
| E-Rickshaw (P) | 28,154 | 39,504 | -11,350 | -28.73% | 28,946 | -2.74% |
| E-Rickshaw with Cart (G) | 7,742 | 7,447 | 295 | 3.96% | 7,425 | 4.27% |
| Three-wheeler (Goods) | 13,133 | 10,322 | 2,811 | 27.23% | 14,006 | -6.23% |
| Three-wheeler (Passenger) | 57,767 | 42,326 | 15,441 | 36.48% | 59,283 | -2.56% |
| Three-wheeler (Personal) | 112 | 142 | -30 | -21.13% | 117 | -4.27% |
| Passenger Vehicle | 407,355 | 363,028 | 44,327 | 12.21% | 440,144 | -7.45% |
| Tractor | 75,109 | 60,956 | 14,153 | 23.22% | 82,080 | -8.49% |
| Construction Equipment | 6,348 | 6,494 | -146 | -2.25% | 6,906 | -8.08% |
| Commercial Vehicle | 99,339 | 86,364 | 12,975 | 15.02% | 102,536 | -3.12% |
| LCV | 55,949 | 475,120 | ###### | -88.22% | 59,379 | -5.78% |
| MCV | 9,177 | 7,222 |
Tejas Cargo Deploys Blue Energy Motors Electric Trucks
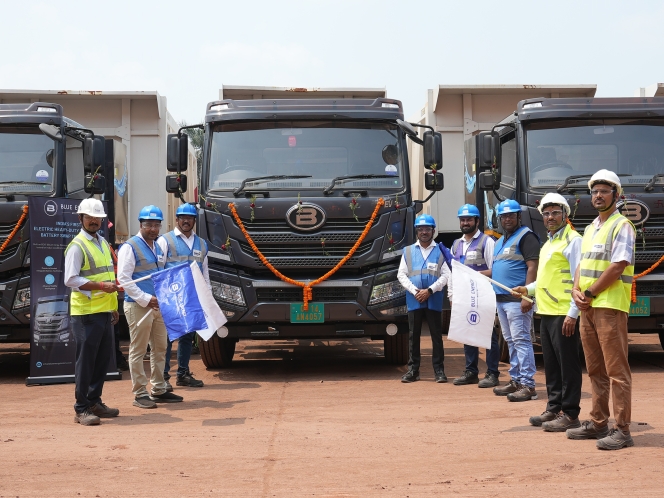
Tejas Cargo has added a Blue Energy electric heavy-duty trucks to its fleet. The e-trucks will cater to the needs of Dalmia Cement logistics requirements with an eye on reducing the carbon footprint. The deployment underlines the growing need of various industrial sectors such as cement, e-commerce etc. to reduce transportation-related emissions and build a more sustainable supply chain. AIFI’s 2nd Annual Conference Focuses On ‘China Plus One’ Opportunity For Indian Forging Sector
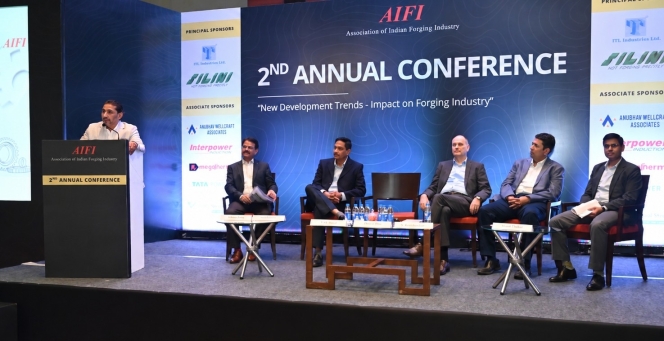
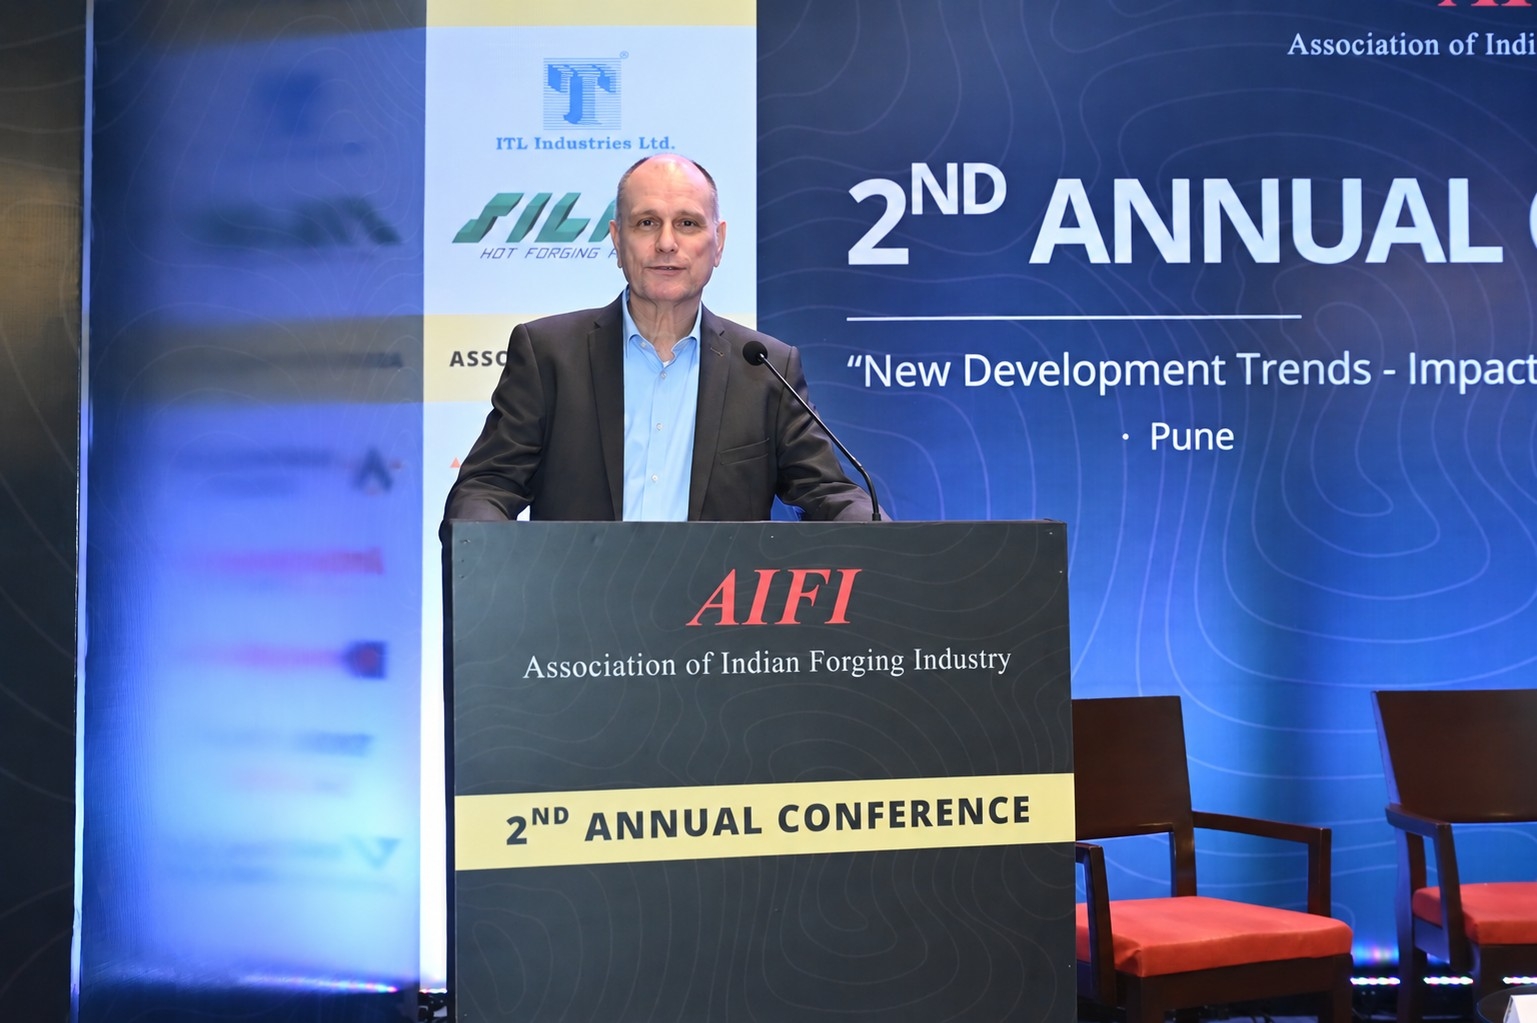
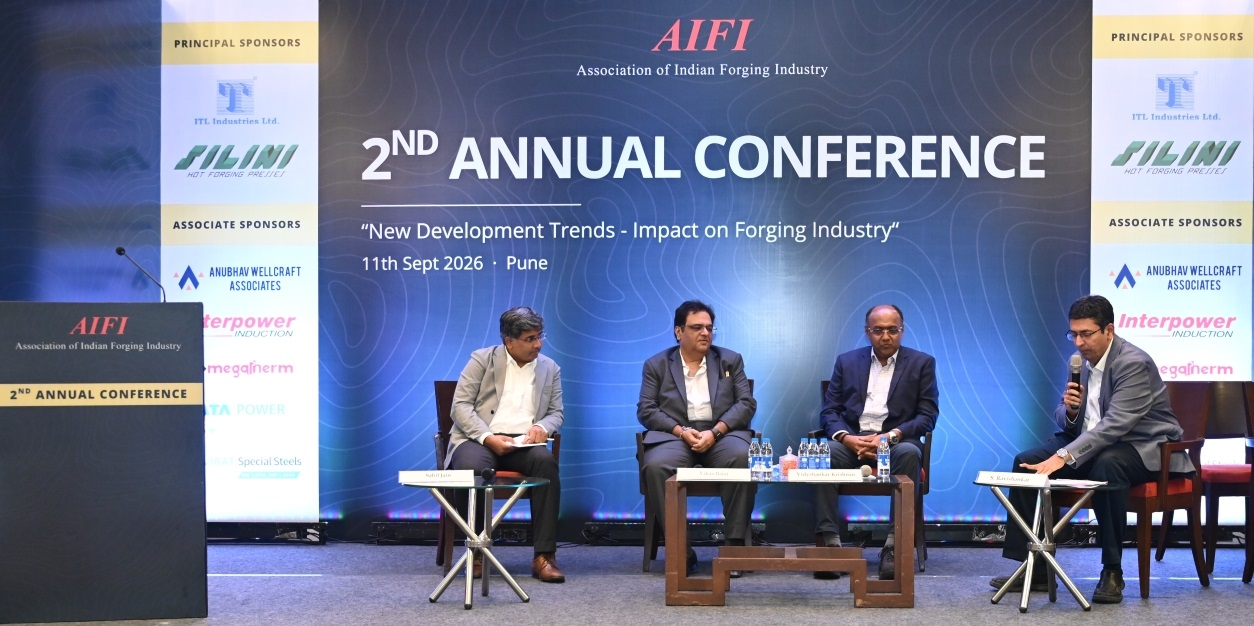
The Association of Indian Forging Industry (AIFI), the apex body of the Indian forging sector, hosted its 2nd Annual Conference on ‘New Development Trends – Impact on Forging Industry’. The event gathered leading stakeholders to discuss the evolving business environment, the China Plus One opportunity, technology and automation, productivity, manpower, rising input costs and the need for greater resilience and competitiveness. Discussions stressed that the industry stands at a pivotal moment to strengthen its place in global value chains as companies diversify supply sources. However, it must move beyond traditional manufacturing models by investing in technology, automation, engineering, R&D, skilled manpower, productivity and sustainability. The consensus was that while India has the base, talent and market opportunity, forging firms must build capability to manage uncertainty and deliver higher-value solutions. Chief Guest Thomas Dose, Managing Director, BMW Group Plant Chennai, highlighted India’s growing global relevance under the China Plus One strategy. He noted that geopolitical turbulence and single-supplier risks are pushing global companies to diversify, giving India a strong chance to become the preferred destination, with customers seeking greater engineering and end-to-end responsibility.
Sunil Javalekar, Chairman, Western Region, AIFI & CEO, S. B. Forgetech Pvt. Ltd., gave the welcome address. Yogesh Thakar, Executive Director, PwC, presented ‘Indian Forging Industry – Next Global Edge’. The memento presentation and vote of thanks were delivered by S Ravishankar, Vice President, AIFI & MD, Super Auto Forge Pvt. Ltd. A panel on ‘Managing Uncertainty / Challenges to Capitalize on Demand Surge’ was moderated by S Ravishankar, with Vidyashankar Krishnan, CMD, M.M. Forgings Ltd.; Vikas Bajaj, MD, Bajaj Motors Ltd. and Sahil Jain, CEO, Hirschvogel Components India Private Limited. Discussions covered GST, manpower, automation, technology upgrades, investments, training, contingency planning, R&D, productivity, demand management and rising input costs. The conference reinforced the industry’s significant opportunity as global supply chains evolve. AIFI continues to unite stakeholders, facilitate knowledge exchange and represent the forging fraternity, with a renewed commitment to competitiveness and growth in domestic and global markets.
Addressing the gathering, Yash Munot, President, AIFI & CEO, Varsha Forgings Pvt. Ltd., said, “The Indian forging industry is at an important juncture, with global supply-chain realignments creating significant opportunities for India. At the same time, we must remain prepared to navigate geopolitical uncertainty, rising input costs, technology disruption and changing customer requirements. Our focus must be on increasing productivity, accelerating technology adoption, developing our people and strengthening innovation and sustainability. The opportunity before the Indian forging industry is significant, but we must build the capabilities and competitiveness required to become a stronger and more valuable partner to global customers.” Thomas Dose, Managing Director, BMW Group Plant Chennai, said, “We believe India should be the Plus One. India has engineering talent, a large market and a very capable forging industry. But China Plus One is not only about supply; we want to see much more partnership from India. Customers are looking for capable partners who can take responsibility, contribute to engineering and development and become part of the development process. India is no longer just a supply chain; Indian companies need to be part of our development. The challenge is to connect the capabilities that are already there, and AIFI has a major role to play in this.” High-Octane Drama And Teenage Brilliance Light Up Kari Motor Speedway
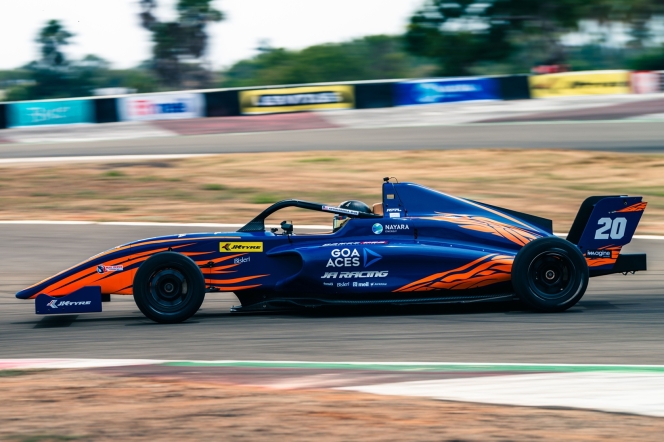
Powered by JK Tyre, the Indian Racing Festival 2026 got off to a thrilling start at the Kari Motor Speedway (KMS) in Coimbatore, recently, with the opening round of the F4 Indian Championship delivering three action-packed races and a closely contested battle for the top honours. Roland Berger Study Highlights EUR 20 Trillion Tech Market Potential By 2040
Thirty emerging technology fields will drive global economic growth over the next 15 years, with their total market value projected to expand from EUR 2.5 trillion to more than EUR 20 trillion by 2040 says a report by global consulting firm Roland Berger. The research titled ‘The 2040 Technology Gameplan ’ finds that these sectors will account for 37 percent of global industrial value creation by 2040, up from 9 percent today. The study identifies 14 core technology areas as critical for industrial growth, representing a market potential of EUR 16 trillion. Semiconductors, artificial intelligence (AI) systems and data centres are projected to constitute more than half of this total. Additional sectors highlighted include energy storage, quantum technologies and humanoid robotics. Furthermore, the report points out that Europe could capture approximately 20 percent of the global market across these 14 primary technology sectors by 2040, equivalent to EUR 3 trillion in value creation. However, European industry has lost market share to the United States and China due to scaling constraints, capital limitations and institutional complexity. To address these challenges, the analysis outlines three approaches tailored to specific technology fields: pursuing global leadership in areas such as quantum technology, medical technology, microgrids and carbon capture; leveraging domestic demand in sectors like autonomous defence, humanoid robotics and charging infrastructure; and attracting foreign technology providers to establish local operations for large language models and next-generation semiconductors. Felix Mogge, Partner, Roland Berger, said, "Europe faces a clear mandate for action. Policymakers and industry leaders must work together to create the right conditions for investment and scaling. Otherwise, the value creation generated by the next wave of technology trends will take place elsewhere." The study indicates that existing European regulatory frameworks, including the AI Act, the EU Battery Regulation, and the European Chips Act, have not fully achieved their targets. The findings call for EU-wide policies to support commercial scaling, capital availability, and industrial strategy across member states. Stefan Riederle, Partner, Roland Berger, said, "Europe has the technologies and the talent to compete for global leadership in a number of fields. The challenge now is to choose the right strategy for each technology area and secure Europe’s long-term competitiveness." Current IssueSubscribe For NewsletterEventsPopular news
| |||
Comments (0)
ADD COMMENT